Existing Loan
Lender, balance, rate, term and payment, pulled from the borrower's closing documents and statements, not re-keyed.
Licensed Florida Real Estate BrokerageIntegrated Closing ServicesMLS AccessBuy With or Without an Agent
Every year, about 2% of every mortgage portfolio turns over. Half refinance. Half move.
Most lenders have invested heavily in refinance retention. Almost none have built a strategy to retain borrowers through the home-sale journey.
HomeJam fills that gap. From the first home-value estimate through the next mortgage, we help lenders stay connected to borrowers before someone else does. And when they are ready, the referral arrives with the file already built.
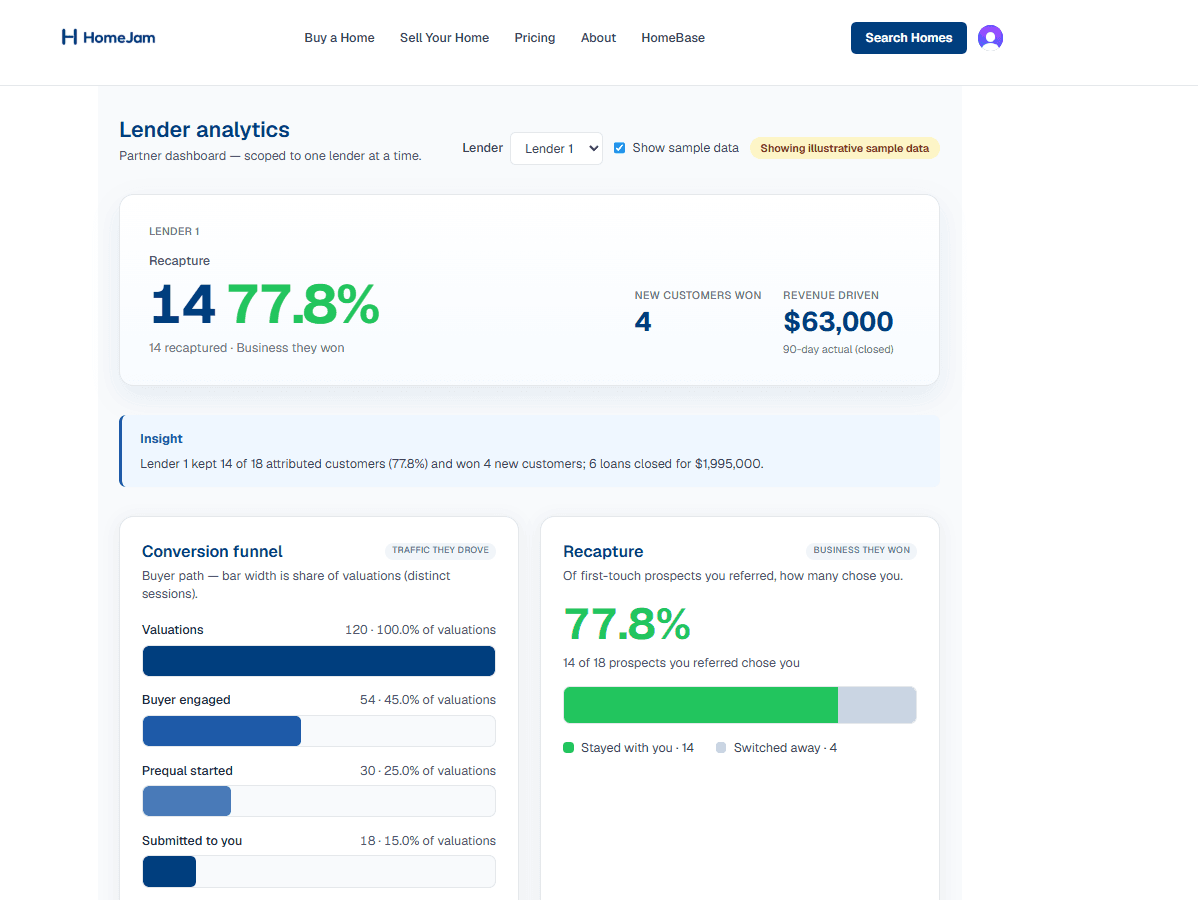
Sample dashboard. Illustrative figures, not client results.
Recapture
Customers Retained
Revenue Driven
Prequalification Requests
Built for banks, credit unions, and mortgage lenders that want to retain more borrowers, not buy more leads.
Built for
Mortgage Portfolio
2%
Annual Turnover
1% Refinances
1% Homes Sold
Most lenders have optimized refinance retention for years. Very few have a home-sale retention strategy. That gap is where servicing relationships are quietly lost, and it is the opportunity the HomeJam Mortgage Recapture Platform solves.
The largest companies in mortgage and real estate are investing billions to own more of the homeownership journey. In 2025, Rocket Companies, the nation's largest mortgage lender, acquired the real estate brokerage and search platform Redfin in an all-stock deal valued at about 1.75 billion dollars, and introduced pricing that rewards customers who both finance and buy through its combined ecosystem.
The strategy is clear: the customer relationship, not any single transaction, is what creates long-term value.
Regional banks and credit unions do not need to build that ecosystem or buy a brokerage. They simply need the right partner.
Rocket bought Redfin.
Zillow sends buyers to its own lenders.
Compass now routes financing through Rocket.
Launch your own integrated homeownership platform, in weeks, not years.
Why build when you can partner?
Zillow and HomeJam solve different problems. One helps lenders find new consumers. The other helps lenders keep the borrowers they already have.
“The mortgage isn't the asset. The borrower relationship is.”
Your Borrowers Already Want to Move.
The question is whether they move with you.
Step 1
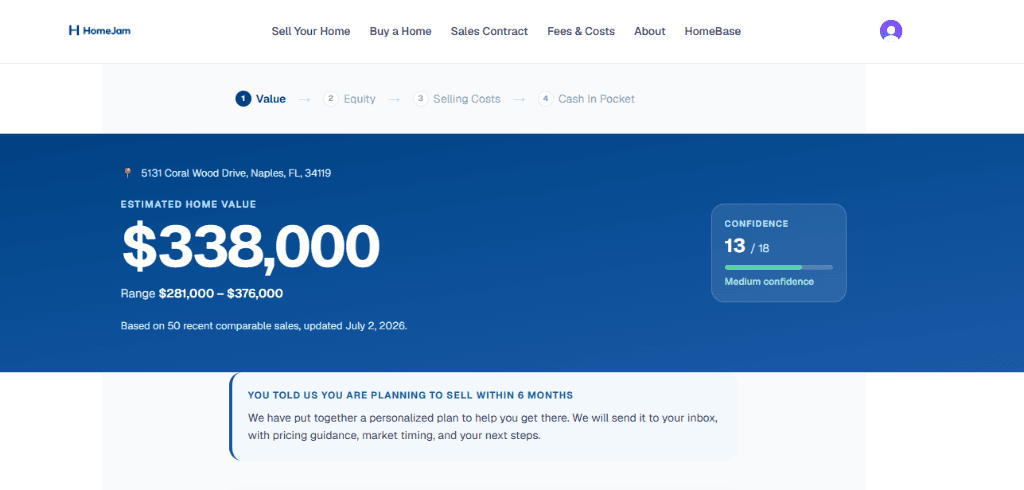
First Touch CapturedThe borrower's first move is checking what their home is worth. When they pull a live estimate through your branded market estimate, HomeJam attributes that borrower to your institution at the earliest possible moment, before any competitor knows they are thinking about selling.
Step 2
Automated EngagementAfter the estimate, the borrower lands in HomeBase, HomeJam's homeowner dashboard, branded to your institution. It holds their home's living record: current value, loan terms, taxes, insurance, maintenance, documents. Market updates and equity insights come from that record, so your institution is present every month, not just at origination.
HomeBase is also where intent shows up first. A value check, an equity view, a rate update opened, a refinance explored: each is a leading indicator your team sees in the dashboard before any application exists.
Step 3
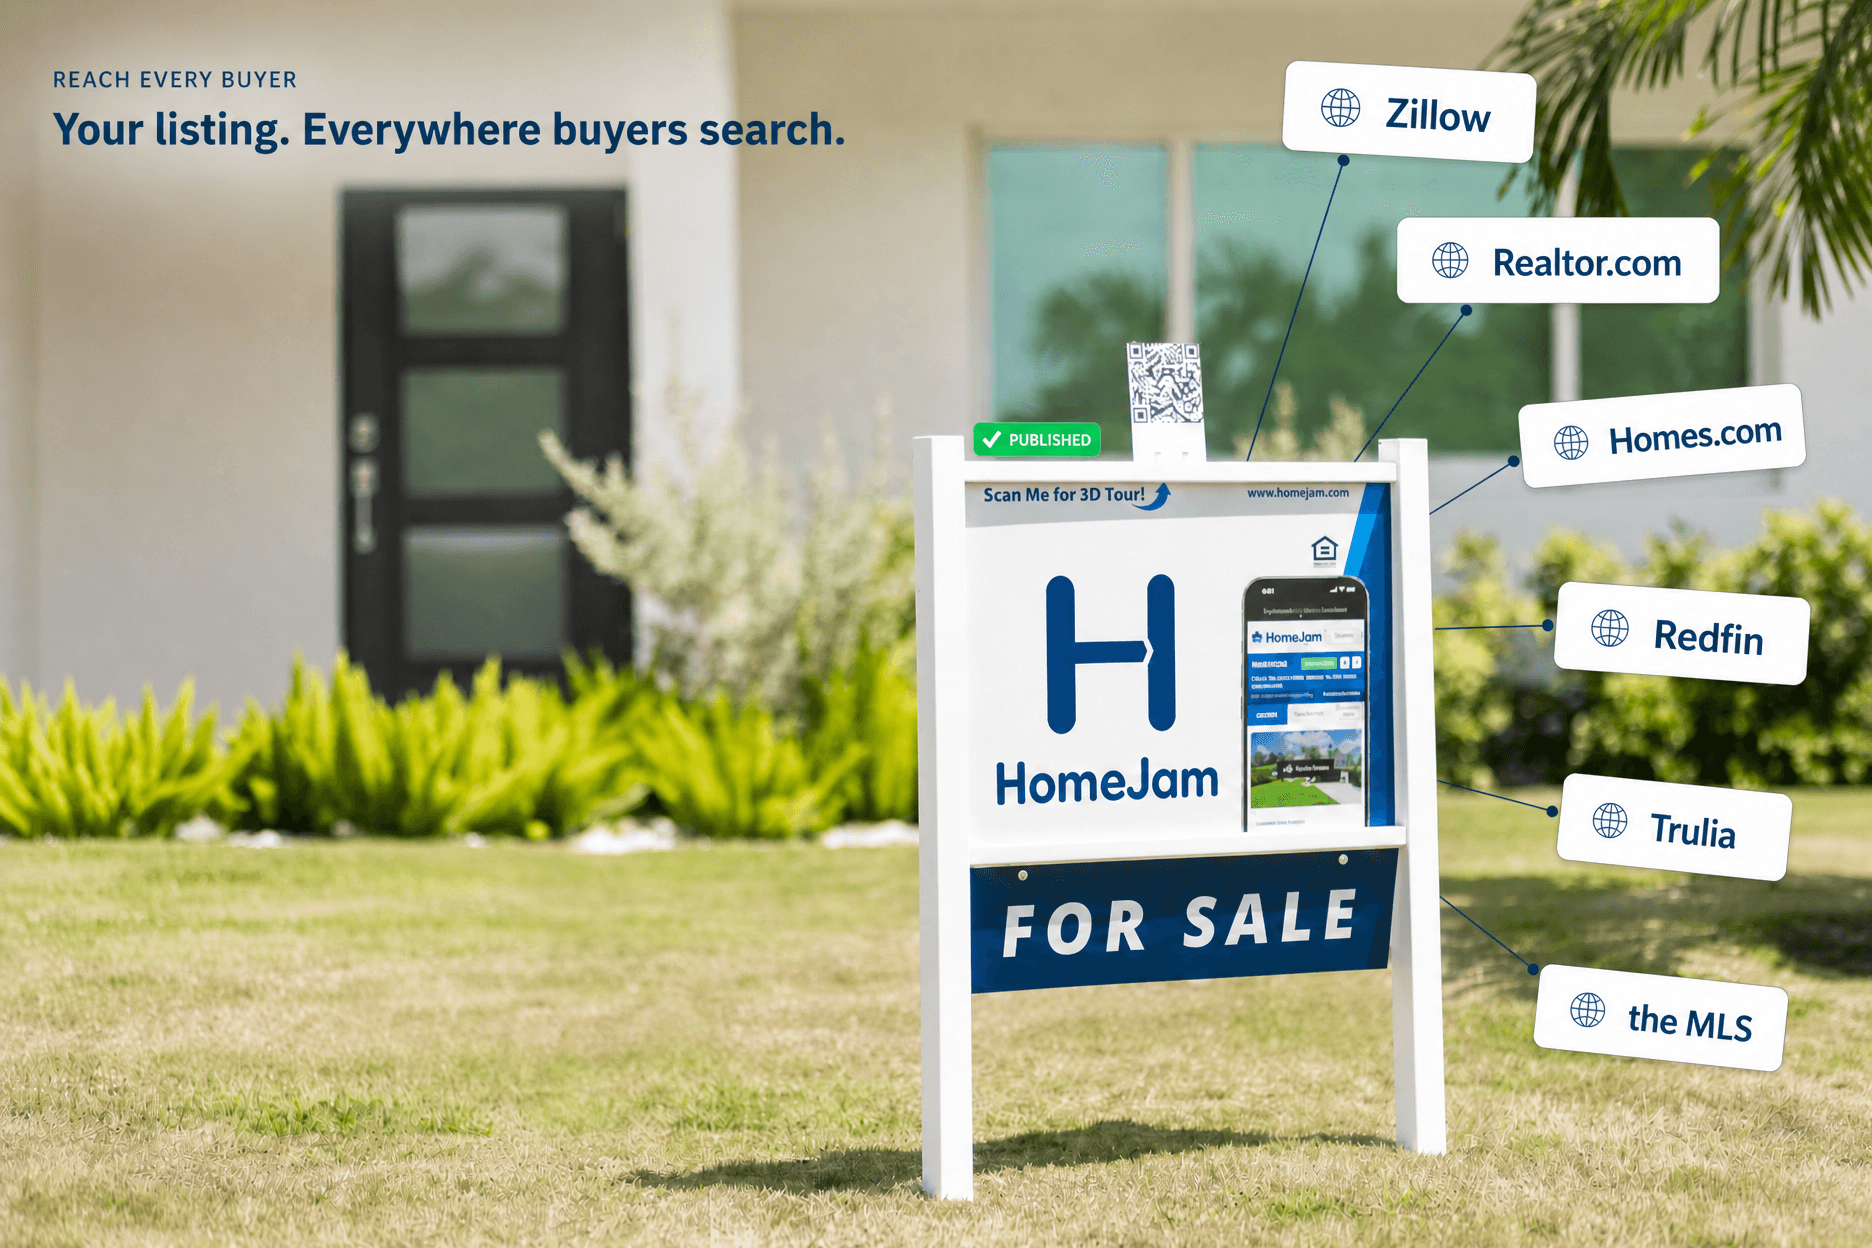
MLS ExposureThe borrower lists their home through HomeJam's licensed brokerage, with full MLS exposure and syndication. The selling side of the move stays inside your ecosystem instead of walking to an unaffiliated agent and lender.
Step 4
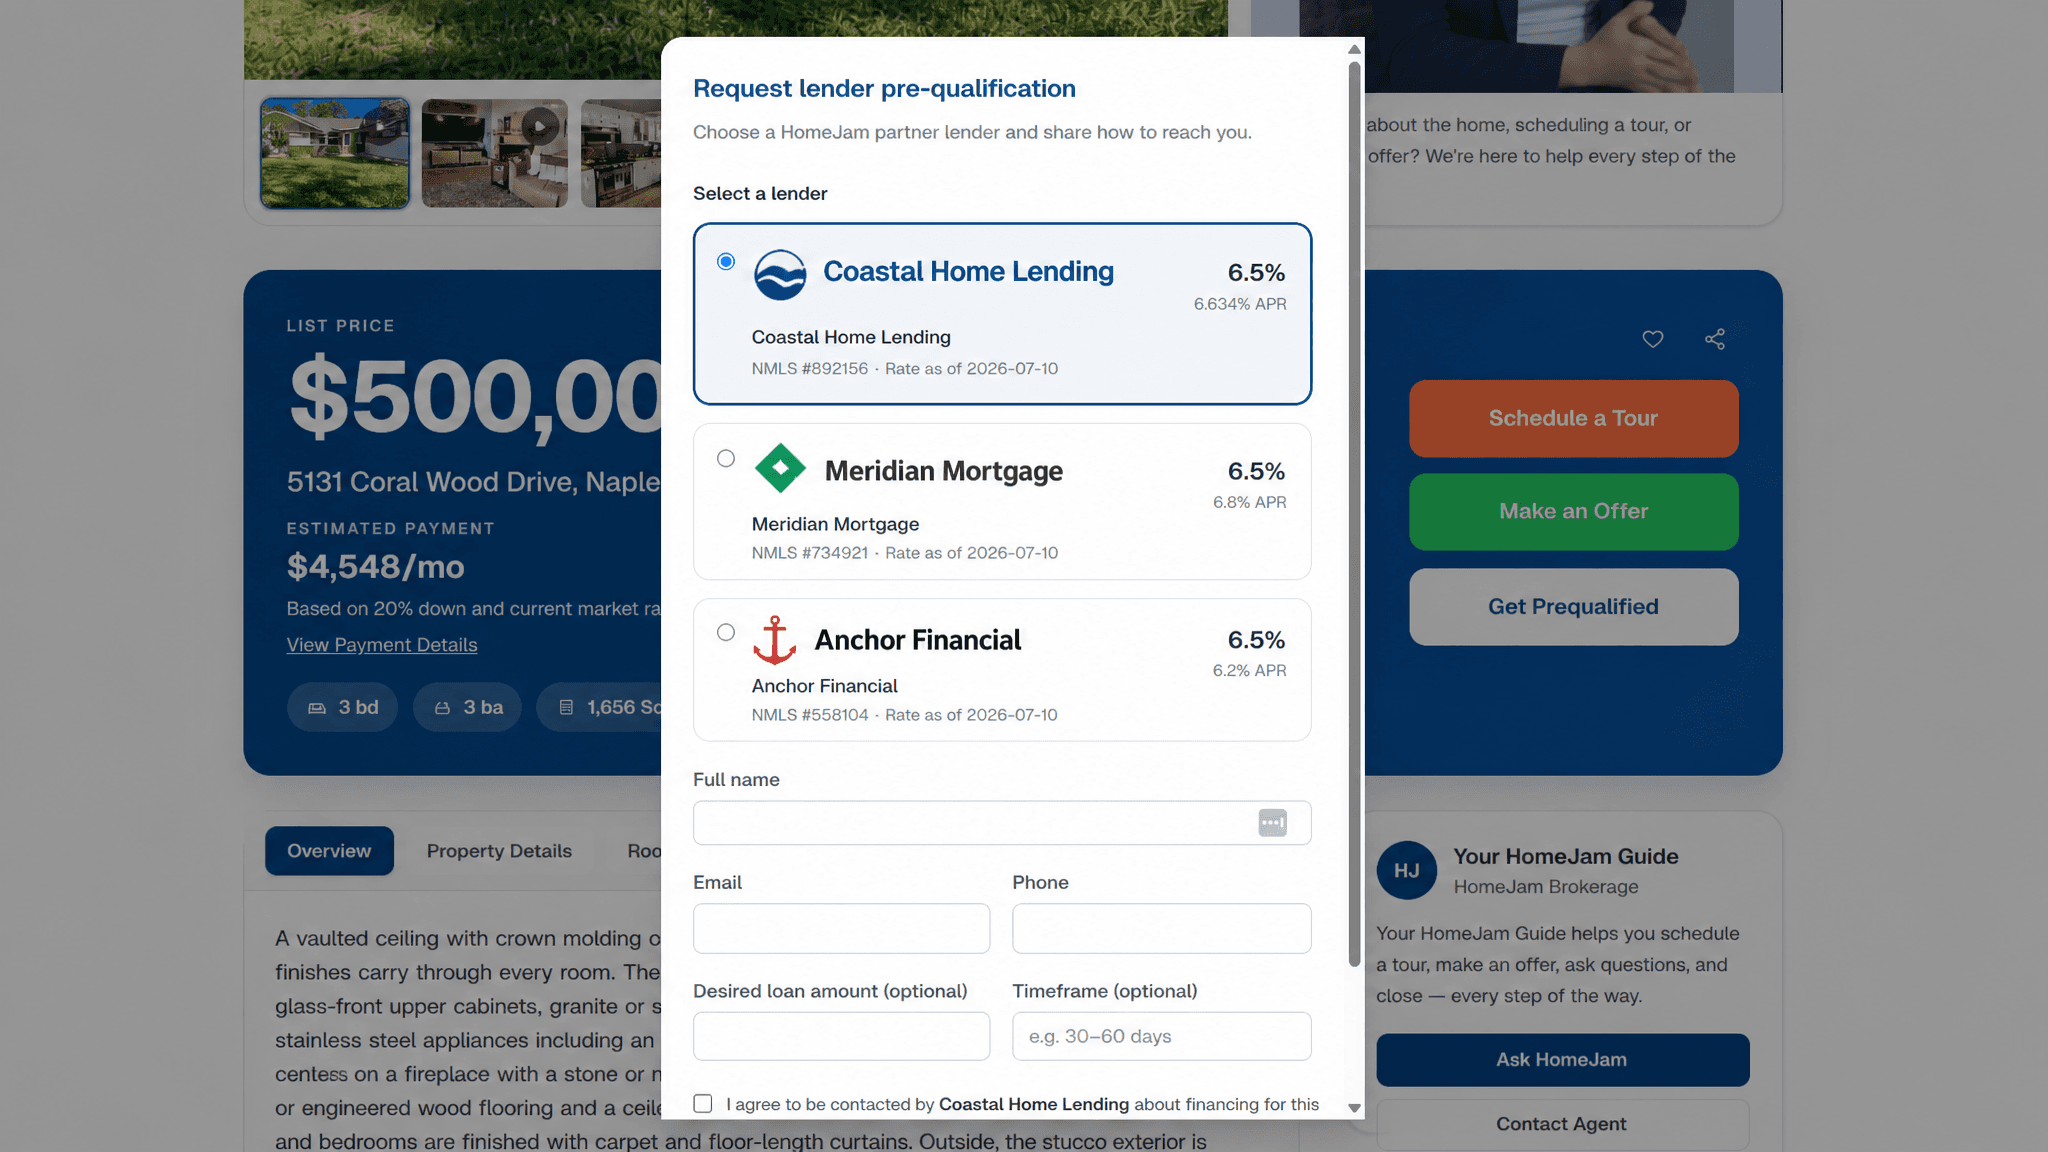
Preferred Lending PlacementWhen the borrower shops for their next home, your institution is presented first in the financing experience, on HomeJam listings and other MLS properties alike. This is the moment the mortgage is recaptured rather than lost.
Step 5
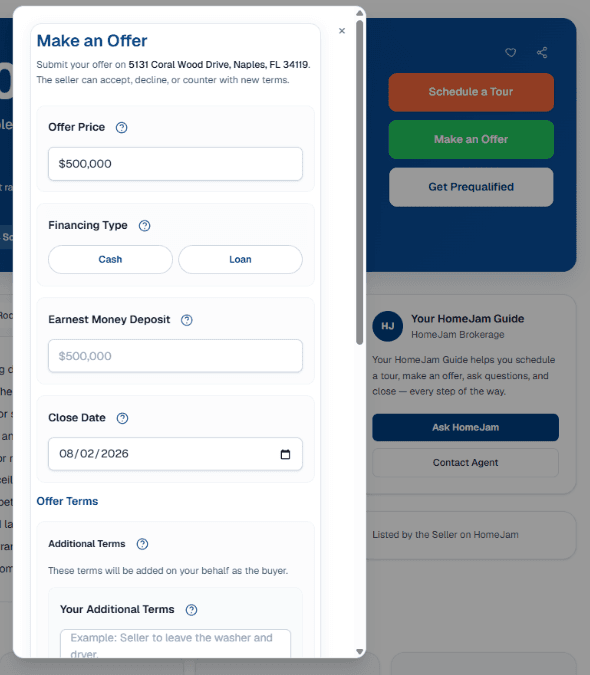
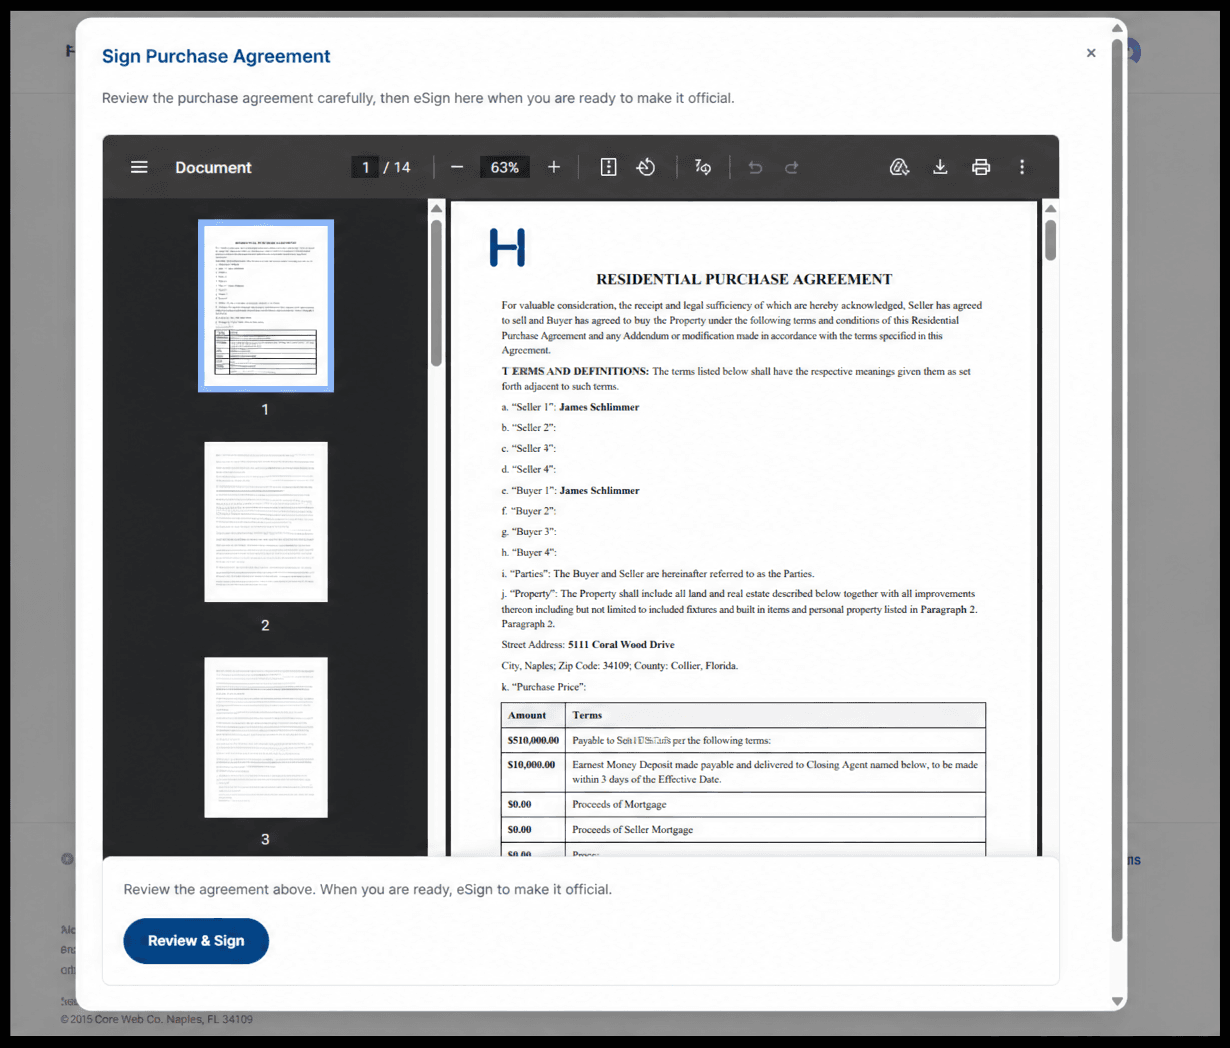
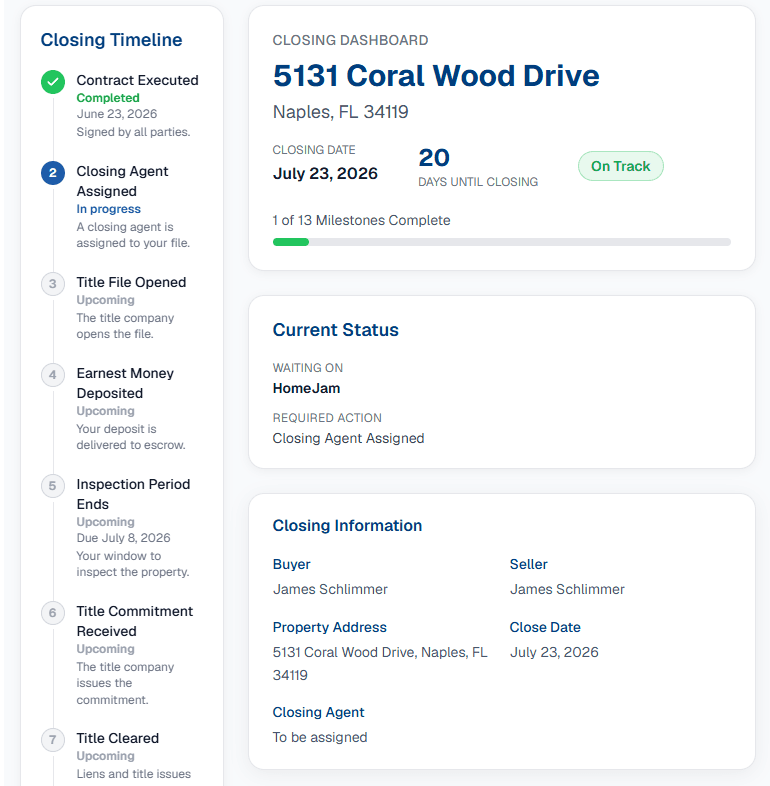
Retained Mortgage CustomerOffer, contract, and closing run through one connected homeownership journey, with your institution engaged the whole way, through to a funded next mortgage and a retained customer.
When a HomeBase homeowner asks to refinance or tap equity, the referral your team receives is not a name and a phone number. It comes with the property and existing-loan file pre-built in MISMO 3.6, the data standard your LOS already speaks, with property characteristics in UAD 3.6 terms, the format appraisals now require.
Lender, balance, rate, term and payment, pulled from the borrower's closing documents and statements, not re-keyed.
Parcel, structure, site, condo or HOA, taxes, insurance and a current value estimate.
The homeowner's request is logged, time-stamped and tied to your institution. No borrower income, asset or credit data; your team collects that as you do today.
Your loan officer starts at step three, not step one.
HomeJam sits around your mortgage stack, not inside it.
Know exactly where every borrower originated.
A branded homeowner dashboard that keeps your institution in front of the borrower every month between transactions, and surfaces leading indicators of intent.
Refinance and equity referrals delivered in MISMO 3.6 with UAD 3.6 property data, ready for your LOS.
Borrowers see your lending options first at prequalification.
Licensed brokerage with MLS listing and portal syndication.
Listing through closing stays in one connected homeownership journey.
Secure APIs deliver borrower activity into your CRM or LOS.
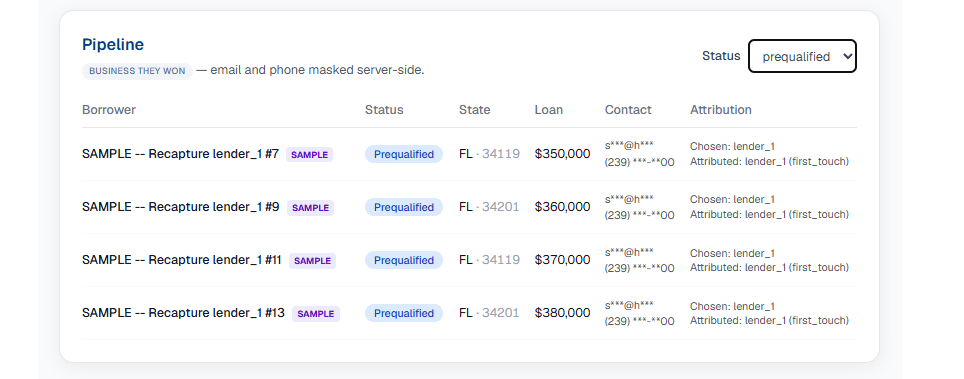
Track recapture rates, revenue generated, active borrowers, attribution, and pipeline health in one dashboard. HomeBase engagement feeds the funnel, so you see leading indicators of refinance and move intent, not just closed loans.
Track valuation requests through recapture percentage in real time.
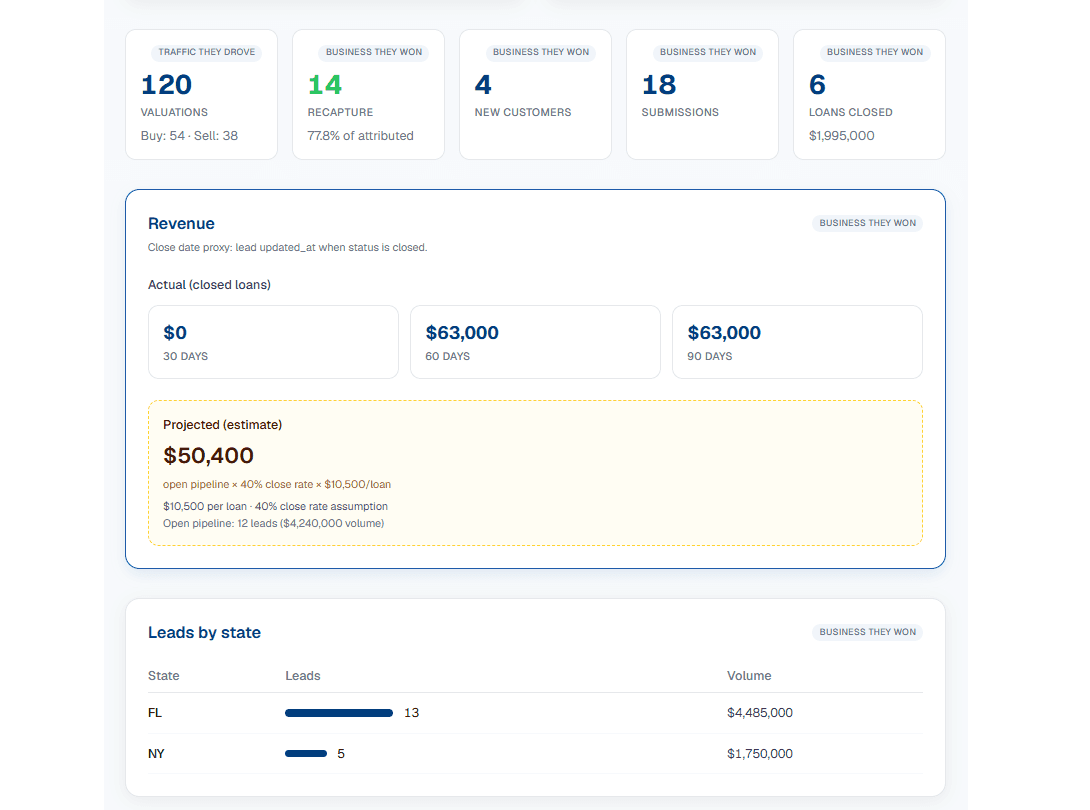
See revenue driven and pipeline value across active borrowers.
Monitor geographic lead volume and closed-loan outcomes.
Sample dashboards. Illustrative figures, not client results.
Secure endpoints deliver qualified borrowers into your systems.
Route attributed leads into your existing CRM workflows.
Referral packages are delivered in MISMO 3.6, so they map to Encompass, Empower, MeridianLink and other LOS platforms without custom translation.
Encryption and authenticated access protect borrower information.
Control who can view, act, and export partner program data.
Full activity history supports compliance and partner oversight.
No. HomeJam sits before and around the mortgage, not inside it. When a borrower is ready for financing, they are delivered back to your existing systems.
Zillow helps lenders compete for anonymous consumers. HomeJam helps lenders retain borrowers they already have. Instead of buying new leads, HomeJam protects existing customer relationships through the home-sale journey.
Building this in-house requires MLS infrastructure, brokerage operations, transaction management, attribution, AI engagement, compliance, and API integrations. HomeJam already provides the complete ecosystem, so lenders can launch in weeks instead of years.
Yes. HomeJam works with the existing real estate ecosystem. Borrowers can list directly, work with a HomeJam listing advisor, receive offers from any licensed buyer's agent, or sell traditionally if they prefer. HomeJam is designed to increase borrower retention, not replace agents.
Listings go on the MLS, which syndicates to major real estate portals through standard MLS distribution.
Yes. As part of partner onboarding, HomeJam is built to deliver qualified borrowers into your CRM or LOS through a secure API integration.
HomeJam is built on an authenticated, role-based access model with encryption and full audit logging.
Borrowers can explore homes across the market while staying connected to their preferred lender throughout financing.
Servicing-platform integration is scoped during partner onboarding. HomeJam is built to connect to the systems you already run rather than replace them.
Yes. HomeJam is designed to complement your marketing automation, adding home-value and home-sale engagement that your current tools do not cover.
Because the ecosystem is already built, partners onboard in a fraction of the time that building in-house would take. Exact timelines are scoped during onboarding.
Yes. HomeJam supports multiple branches and regions under a single institution.
No. Borrowers always choose. HomeJam works alongside the existing real estate ecosystem, and borrowers can list, buy, and finance the way they prefer.
Property details, the existing loan's terms and estimated balance, taxes, insurance and a current value estimate, formatted in MISMO 3.6 with property characteristics in UAD 3.6 terms. It never includes borrower income, assets or credit; your institution collects those directly.
No. HomeJam provides property data in the UAD 3.6 vocabulary appraisers use, which can speed an appraisal order. Appraisals are performed by licensed appraisers your institution engages.
Reserved for Launch Partners
Tell us about your institution and we will follow up with launch partner onboarding details.
Help define the next generation of borrower retention. Protect more customer relationships, increase mortgage recapture, and launch in weeks, not years.
We use cookies and similar tools to remember how you found us, keep a session identifier, and understand which property pages you view. You can accept this use or decline optional tracking. See our privacy notice.